Do you lay awake at night worrying about money? Do you avoid checking your bank balance because it gives you anxiety? If this sounds familiar, know that you’re not the only one who feels overwhelmed and lost when it comes to personal finance.
The truth is, most people struggle to some degree with budgeting, saving, debt, and investing for the future. It’s completely understandable too – money management is complicated!
But here’s the good news: you can absolutely take control of your finances, even if you’re starting from zero. With the right strategies laid out step-by-step, you can transform your relationship with money and find real financial peace of mind.
In this comprehensive guide, I’ll walk you through the basics of personal finance in a simple, practical way that anyone can understand. We’ll cover how to create a budget that actually works, build up an emergency fund, improve your credit, tackle debt head-on, learn investing basics, and plan for a comfortable retirement.
You don’t need to be a math genius or finance expert to implement these steps. I’ll break it down into bite-sized, approachable chunks so you walk away with real skills to take the stress out of managing money.
Are you ready? Let’s get started on a straightforward path to getting your finances under control!
Why You Need a Budget
Budgeting is the foundation of any good financial plan. Without a budget, it’s easy to overspend and fall into debt. A budget gives you awareness and control over where your money is going each month.
Here are some key reasons to start budgeting:
- Avoid getting blindsided by expenses
- Identify areas to cut spending and save more
- Track your progress toward financial goals like debt payoff or buying a home
- Prevent fighting with your spouse about money
- Reduce stress and sleep better knowing your finances are under control
How to Make a Simple Budget
“A budget is telling your money where to go instead of wondering where it went.” – Dave Ramsey, Financial Expert
As Dave Ramsey highlights, a budget gives your dollars a job and purpose. Without budgeting, it’s easy to look back each month and wonder where all your money went. A budget assigns those dollars ahead of time so you intentionally direct funds towards your priorities rather than wondering after the fact.
Follow these steps to create your first budget:
1. Calculate Your Net Monthly Income
Tally up income from your job, side hustles, and any other sources after taxes and deductions. This is the total amount you have to work with each month.
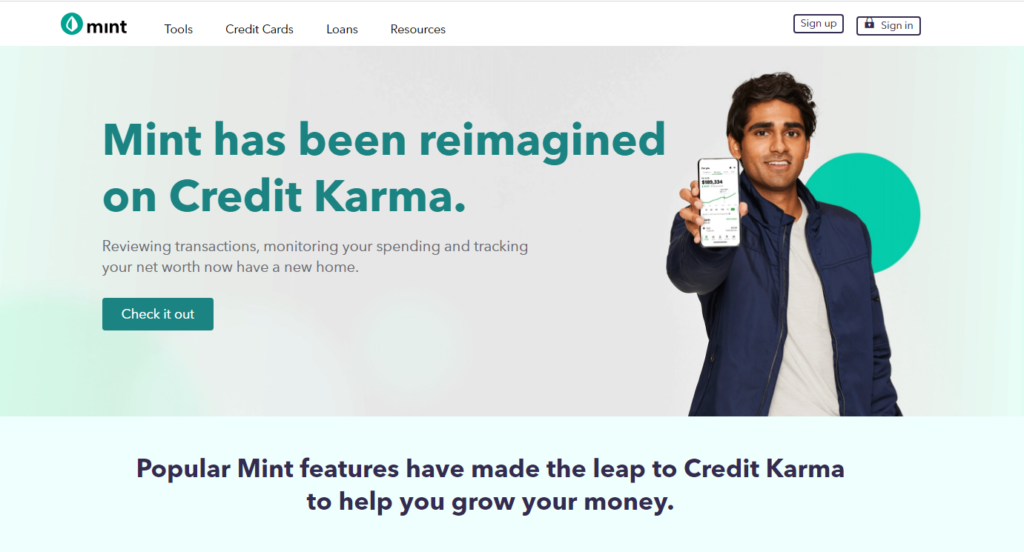
Tools like Mint, YNAB, or EveryDollar can help create budgets and track spending. Or use a spreadsheet to build your own budget from scratch.
For example, you can use a Google Sheet with columns for income, fixed expenses like rent, variable expenses like dining out, and savings goals. Assign dollars to each area and see if expenses exceed income.
2. Track Your Actual Spending
Apps like Mint and Personal Capital can automatically pull transactions from linked accounts to track spending. You can also use an Excel or Google Sheet to manually log expenses under categories like grocery, gas, utilities, etc.
For example, record all spending in a spreadsheet for 2 months to analyze spending habits and inform your budget setup.
3. Categorize Your Spending
Use a budgeting app or spreadsheet to divide expenses into categories like:
- Fixed: rent, car payment, utilities
- Variable: dining out, groceries, gas
- Debt: student loans, credit card payments
- Savings: emergency fund, retirement
Mint and YNAB make it easy to categorize transactions and see spending patterns.
4. Set Limits for Each Category
For instance, based on average utility bills, allot $150/month for electricity and gas spending. Or cap dining out at $200/month based on restaurant spending habits.
Excel or Google Sheets allow you to set category limits and track amounts remaining.
5. Find Ways to Save
Call internet and cable companies to negotiate lower rates. Meal plan and use grocery loyalty apps to lower food costs. Unsubscribe from unused monthly services.
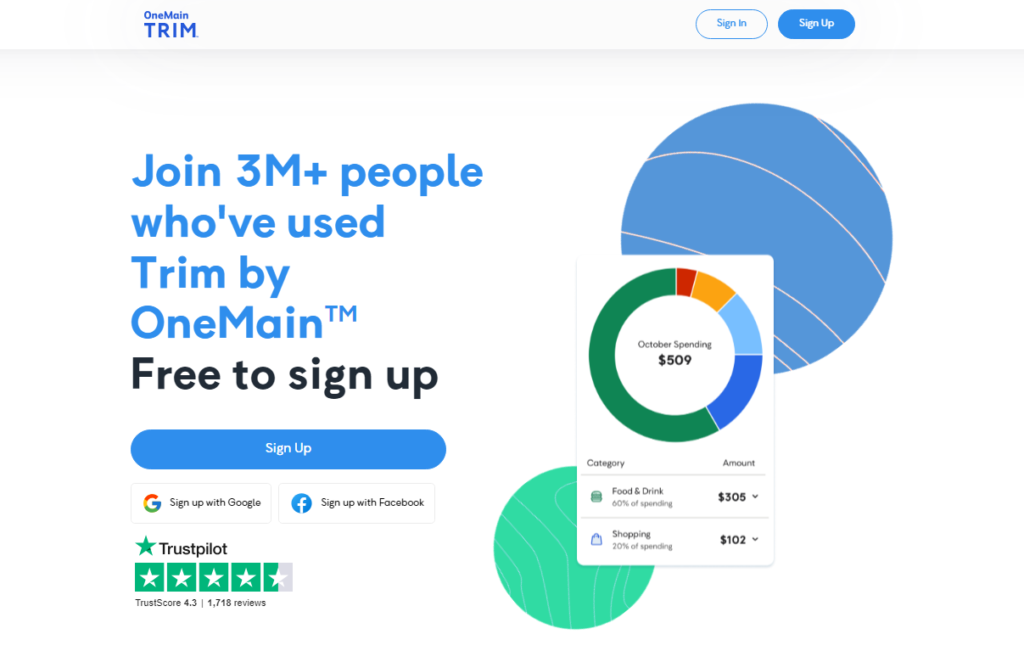
Apps like Trim analyze bills and negotiate discounts on recurring services to find savings.
6. Use the Budget as Your Money Map
Check your budget category balances in Mint before making purchases. Or review your custom spreadsheet to ensure you have room in dining out before booking a restaurant.
YNAB has great budgeting workshops and resources to learn systems.
Building an Emergency Fund
Life happens. Cars break down, jobs are lost, illnesses strike. An emergency fund helps you handle surprises without going into debt. Try to save 3-6 months’ worth of living expenses, but any amount is better than nothing.
Here are tips for building your emergency savings:
- Automate it – Set up automatic transfers from each paycheck so you don’t forget.
- Pay yourself first – Treat your emergency fund contribution like any other fixed bill by funding it at the start of the month.
- Save windfalls – Put tax refunds, work bonuses, gift money, or side hustle earnings straight into savings.
- Ladder CDs – Open multiple short-term certificates of deposit so one matures each month providing cash flow if needed.
- Use a separate account – Open a dedicated high yield savings account to grow your fund faster.
Having an emergency fund brings peace of mind knowing you have a financial safety net when the unexpected strikes.
Improving Your Credit Score
Your credit score impacts everything from interest rates on loans to approval for apartments or jobs. Improving your credit score takes effort but pays off in savings and opportunities.
Follow these credit-boosting tips:
- Pay all bills on time – Set up autopay or reminders to avoid late payments that lower your score.
- Keep balances low – High balances relative to your limit hurt your credit, so pay off cards monthly if you can.
- Limit credit inquiries – Don’t open multiple new accounts rapidly since applying lowers your score temporarily.
- Correct errors – Dispute any inaccuracies on your credit report to maximize your score.
- Become an authorized user – Ask a family member with good credit to add you to a longstanding account.
Monitoring your credit score lets you see the impact of your credit management habits over time. With diligence, you can achieve an excellent score and reap the rewards.
Strategies for Paying Off Debt
From student loans to credit cards, debt hangs over many people’s finances. Paying off debt takes discipline but frees up cash to use toward other goals.
Here are methods to tackle debt:
- Avalanche method – Pay minimums on all debts except the one with the highest interest rate. Put extra money toward paying off that debt first.
- Snowball method – Pay minimums on all debts except the one with the lowest balance. Attack the small debt first for quick wins and motivation.
- Balance transfer card – Transfer balances to a 0% interest card to avoid interest and pay down the principal.
- Debt consolidation loan – Combine debts into one payment at a lower interest rate.
- Budget and cut expenses – Free up more money to devote to debt repayment.
- Earn more income – Get a raise, pick up a side gig, or sell unused items to speed up paying off debt.
Investing Basics to Know
Investing allows your money to work harder and is essential for building long-term wealth. As a beginner, stick to the fundamentals:
- Understand compound interest
Earning interest on your interest accelerates growth. Starting early lets compounding work its magic.
- Know your risk tolerance
How much volatility can you stomach? More aggressive investments offer higher potential returns but larger losses.
- Diversify your investments
Spread money across different assets classes, sectors, markets and risk levels. Diversification reduces risk.
- Be consistent
Invest regularly, like monthly, over decades. Time in the market is more important than timing the market.
- Keep costs low
High fees reduce gains. Index funds and ETFs offer broad market exposure at low cost.
- Reinvest dividends
Plowing dividends back into investments compounds your earnings.
Taking the time to learn investing fundamentals will pay off for decades to come.
Preparing for Retirement
Retirement may seem far away, especially when you’re just starting out. However, planning early maximizes your investment returns through compound growth. It also gives you more flexibility to adjust savings and investing behavior.
Here are tips for preparing for retirement:
- Start NOW – Time is your biggest asset. Start contributing even small amounts today.
- Contribute to retirement accounts – Max out contributions to 401(k)s, IRAs and other tax-advantaged accounts.
- Capture employer match – Take full advantage of any matching contributions from your employer.
- Increase contributions over time – Boost savings rate as income rises. Budget to save at least 10-15% toward retirement.
- Develop multiple income streams – Build income from rental properties, side businesses, or investments to fund retirement.
- Pay down debt – Entering retirement debt-free gives you more flexibility.
- Delay Social Security – Wait until age 70 if possible to maximize this inflation-protected income stream.
Planning a decade or more in advance makes reaching your retirement goals more attainable. Implement these tips to help ensure a comfortable retirement.
Actionable Steps
Here are some practical, step-by-step strategies tailored to different demographics:
For College Students:
- Track spending to create a budget
- Build emergency fund savings even if only $5-10 per month
- Pay credit card bill in full each month
- Pay down high interest student loans
- Take advantage of 401(k) match if offered in college job
- Start investing small amounts in a Roth IRA
For Young Adults:
- Create monthly budget tracking all income and expenses
- Build emergency savings fund of 1-3 months expenses
- Contribute to 401(k) up to full employer match
- Pay down credit card and student loan debts
- Begin investing consistently toward retirement in Roth IRA or 401(k)
- Limit housing expenses to less than 30% of income
For Families:
- Review insurance needs and update beneficiaries
- Establish college savings accounts like 529 plans
- Discuss financial goals and strategies with spouse
- Balance saving for kids’ education with retirement
- Adjust spending habits and budget for growing family
- Discuss money management principles with kids
For Pre-Retirees:
- Accelerate retirement account contributions
- Develop retirement income plan from Social Security, pensions, savings
- Pay off mortgages and high interest debts
- Discuss retirement lifestyle goals and expenses
- Identify gaps and adjust savings or lifestyle to meet target retirement income
- Consult retirement planning advisor and tax expert
Common Mistakes to Avoid
It’s easy to make missteps when managing your finances. Here are some common pitfalls to watch out for along with tips to steer clear:
Not budgeting or tracking where your money goes each month
- Use budgeting apps or spreadsheets to track every expense
- Categorize spending to see where the money is going
- Review bank and credit card statements to inform the budget
Living beyond your means and accumulating unhealthy debt
- Create a budget aligned with your actual income
- Cut discretionary spending on wants until debt is reduced
- Downsize housing, vehicles, and lifestyle to income level
Not paying credit card bills in full and carrying balances
- Pay credit cards in full each month
- Transfer balances to 0% APR cards to save on interest
- Increase monthly payments well above minimum
Not saving for emergencies or retirement consistently over time
- Automate savings contributions from each paycheck
- Start small if needed but commit to saving consistently
- Increase savings amount whenever you get a raise
- Treat savings as a fixed monthly bill
Trying to time the market instead of staying invested long-term
- Invest for long-term growth using dollar cost averaging
- Remain invested through market ups and downs
- Avoid panicking and selling when markets decline
Paying excessive investing fees that eat away at returns
- Use low-cost index funds and ETFs instead of expensive mutual funds
- Opt for passively managed funds over active management
- Review fees and reduce portfolio costs
Having no idea what you actually spend each year in retirement
- Track spending diligently leading up to retirement
- Build detailed retirement budget based on actual costs
- Stress test budget at different spending levels
Not accounting for healthcare, long-term care costs and rising inflation
- Factor in health insurance premiums, copays, LTC needs
- Use higher inflation rate when calculating retirement costs
- Review and adjust estimates yearly
Not communicating openly with your spouse about money management
- Have regular money date nights
- Share financial goals, budgeting, investing, and retirement plans
- Agree on tradeoffs and priorities
Not having proper insurance coverage or updating beneficiaries
- Review policies yearly and adjust coverage
- Update beneficiaries after major life events
- Consider needs for life, health, disability, LTC insurance
Frequently Asked Questions
How do I get started budgeting?
Track your actual spending for 1-2 months first. Use this spending baseline to build your initial budget. Budgeting apps like Mint or You Need a Budget can streamline the process.
What percentage of income should go toward debt repayment versus saving?
Aim to put at least 10-15% toward retirement savings. Allocate any extra income above a basic emergency fund toward aggressively paying down high interest debt.
How much do I need to retire comfortably?
Industry rules of thumb suggest you need 70-90% of your pre-retirement income to maintain your standard of living. Maximize savings, minimize expenses, and use retirement calculators to determine your target number.
Should I pay off student loans or start investing?
Compare your student loan interest rate to the return you could reasonably earn investing. Pay off loans over 4-5% interest before investing. If rates are lower, invest while making regular loan payments.
What are examples of assets I can invest in?
Start with stocks, bonds, ETFs, mutual funds, and real estate. As you gain experience, you can expand into alternative assets like commodities, cryptocurrencies, private equity, hedge funds, and more. Diversify across asset classes to manage risk and maximize returns.
What are common retirement investing mistakes?
Withdrawing too much too soon, not having a well-diversified portfolio, investing too conservatively, carrying excessive debt into retirement, and not coordinating savings with your spouse are some top mistakes. Meeting with a retirement planning advisor can help avoid missteps.
How important is an emergency fund?
Extremely important! Aim to save 3-6 months’ worth of living expenses in a liquid emergency fund. This protects you from going into high interest debt due to expected expenses like medical bills or car repairs and unexpected events like job loss.
Should I make minimum payments on all debts or focus extra money on one?
The avalanche and snowball methods focus all extra payments on one debt at a time to pay off debts faster. Alternatively, you can allocate any extra payments proportionally across all debts based on balance size or interest rate.
What credit score do I need to qualify for the best loan terms?
Aim for a credit score over 760 to qualify for the lowest interest rates and best loan terms. Scores of 700-749 still get you reasonable rates. Anything under 620 makes you a risky borrower so improving your credit is important.
Where should I invest retirement savings?
Target funds or professionally managed accounts handle diversification. Or create your own mix of stocks, bonds, mutual funds, ETFs.
You Have the Power to Take Control
Gaining control of your finances may seem daunting but breaking it down into small, practical steps makes it very achievable. Focus on building healthy money management habits like budgeting, saving, reducing debt, and investing early and consistently.
As emphasized in The One Money Skill The Rich Always Use, living below your means is key to freeing up capital to put toward your financial growth. Avoid lifestyle inflation and overspending. Instead, maximize your savings and let compound interest go to work.
For More Free Videos, Subscribe to the Rhodes Brothers YouTube Channel.
It doesn’t happen overnight, but with discipline and the right strategies, you can take control of your money and work toward achieving your financial goals. Start today by taking one small step, whether saving an extra $20 or reviewing your monthly budget.
Your financial future is in your hands. Make it a bright one by developing strong money skills. You’ve got this! For more useful tips, check out the Rhodes Brothers YouTube Channel.
Resources
- The Total Money Makeover by Dave Ramsey
- The Millionaire Next Door by Thomas J. Stanley
- Financial Peace University
- YNAB
- Mint
- Learn Investing Basics Online
- Retirement Planning Resources
- FICO credit score information
- NerdWallet credit card and debt payoff calculators
- Retirement Planning Blog from Fidelity
Budgeting and Saving Cheat Sheet
- Track every expense
- Categorize spending
- Eliminate nonessential spending
- Budget for needs and savings first
- Automate saving contributions
- Pay yourself first each month
- Save windfalls and tax refunds
- Review and adjust budget regularly
- Build emergency fund of 3-6 months’ expenses
- Contribute 10-15% toward retirement
- Increase savings rate as income grows
- Invest savings for growth